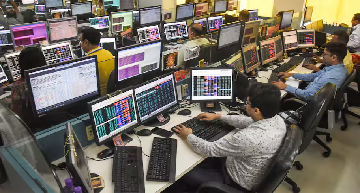

Domestic equity benchmarks opened largely flat on Thursday with Nifty opening around 22,600 mark as gains in IT and pharma stocks were offset by weakness across financial, FMCG and auto stocks.
Nifty opened at 22,599.05, down 4 points or 0.02 per cent.
Similarly, Sensex started at 72,668, up 29.30 points or 0.04 per cent.
Sector-wise, Nifty IT, Nifty MidSmall Healthcare, Nifty Pharma were top gainers with advancing up to 0.59 per cent.
Meanwhile, metal, consumer durables and chemicals also traded marginally higher.
On the other hand, Nifty Financial Services ex-Bank, Nifty FMCG slipped up to 0.38 per cent.
Market experts said the RBI’s calibrated tightening stance could put pressure on equity valuations as higher interest rates make fixed-income investments relatively more attractive.
They also expect investor preference to shift marginally towards relatively interest-inelastic sectors such as pharmaceuticals.
Experts noted that growth stocks have continued to attract investor interest despite high valuations, while value stocks have remained subdued.
“Sustained selling by foreign investors in large-cap stocks, coupled with the US 10-year Treasury yield staying above 5.3 per cent, could keep large-cap stocks under pressure,” they added.
“Yesterday’s multiple attacks at 22574 calls for an extended period of consolidation, before setting a direction. Though considerably weakened, the 23100-220 view is still in play, with downside marker at 22439,” according to them.
Experts added that a sustained reversal in the market trend would require foreign investors to turn buyers, while value stocks could offer opportunities over the longer term.
In addition, foreign institutional investors remained net sellers on Wednesday and offloaded equities worth more than Rs 6,121 crore.
While domestic institutional investors provided some support and purchased equities of around Rs 4,596 crore.
Moreover, market sentiment remained cautious amid concerns over elevated US Treasury yields and oil prices, while Asian markets traded on a cautious note following a softer session on Wall Street.