
Long-time investors are well aware of the nature of investments in Fixed Deposits. They don’t really seek high returns, but a decent gain while keeping aside some money for different purposes, which may include emergencies. However, locking in the entire corpus for the long term may restrict liquidity and limit returns. One interest rate would apply to the entire corpus. Therefore, FD laddering is a good option to ensure liquidity while keeping aside a corpus for savings, even with modest returns.
FD laddering is a strategy which includes dividing the corpus into portions that go into multiple FDs with different tenures and interest rates. It enables liquidity of funds at intervals without having to break the deposit and withdraw the entire sum. While one of the FDs matures, others are still locked in as they continue generating interest.
WHY NOT A SINGLE FD?
It is better than investing the money in a single FD for a long tenure since the entire sum would be out of reach and generating returns at a uniform interest rate, thus limiting the scope. In case of urgent needs, you would need to make a premature withdrawal, which carries a penalty of around 0.5-1 percent on the applicable return rate.
FD laddering also allows investors to take advantage of changing interest rate cycles. An investor can assess the rate cycle and lock in at the peak time as they repeat this with all the portions. Even if that does not happen, the money is exposed to different interest rates.
FD LADDERING STRUCTURE
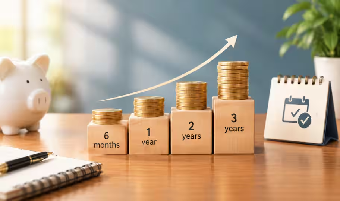
Suppose an investor has a sum of Rs 5,00,000 to invest, which can be divided into 1-year, 2-year, and 3-year FDs. They may allocate the lump sums across these tenures:
— Rs 1 lakh: 1-year FD
— Rs 2 lakh: 2-year FD
— Rs 2 lakh: 3-year FD
The person may also choose FDs with short maturity periods of a quarter or 6 months if the money is needed for a near-term goal.
— Rs 1 lakh: 6-month FD
— Rs 1 lakh: 1-year FD
— Rs 1 lakh: 2-year FD
— Rs 2 lakh: 3-year FD
Either way, the money is constantly growing in other deposits even when one of them matures and is withdrawn.
Following the maturity of one portion, the person may reinvest it in another FD.
Even though the Reserve Bank of India (RBI) kept the repo rates unchanged at 5.25% in its August 2026 Monetary Policy Committee (MPC) meeting, HSBC Global Investment Research predicts a policy rate (repo rate) hike of 25 bps twice, once in October and another in December. A rise in repo rates may push banks to hike FD rates. Investors, in that case, would have the opportunity to make the most of it.